
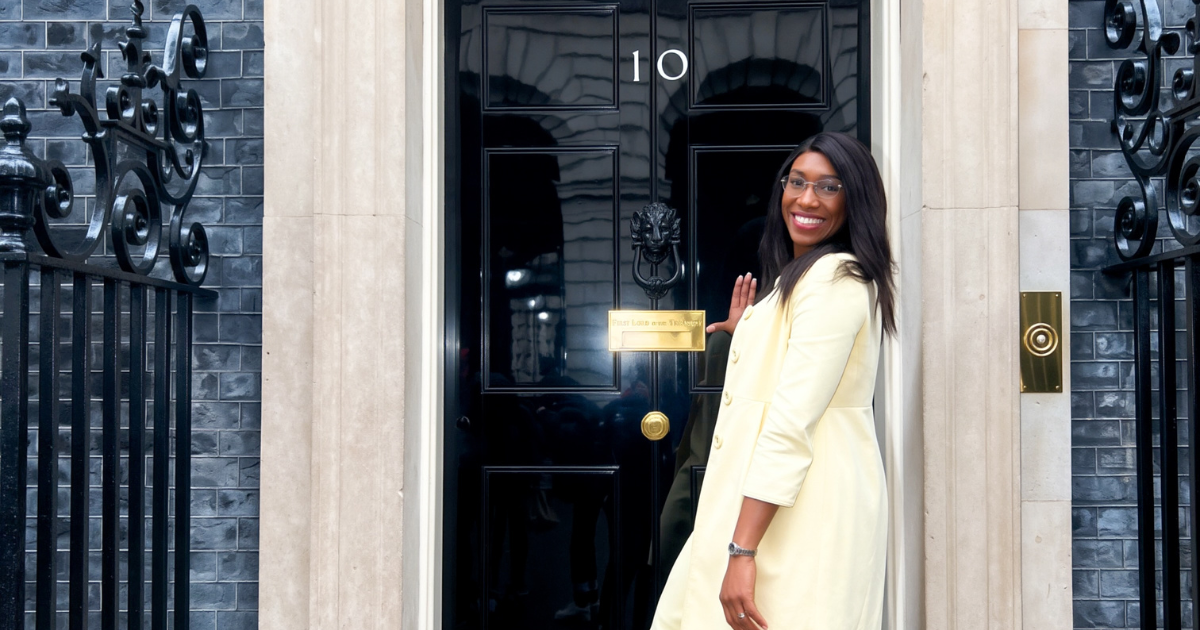
The Budget can leave you with plenty of headlines and very little clarity about your own bank balance.
Do you need to change your savings? Will your wages rise? Is there help with household bills?
Here are the main personal-finance announcements from 28 October 2026, what they could mean in pounds and practical steps to help you plan. This is a selection of the measures most relevant to everyday money decisions.
Timing matters: an announcement is not the same as a change already in force. Several measures below start next year or later and require legislation.
1. Your pay could rise from April
The National Living Wage for workers aged 21 and over is set to increase from £12.71 to £13.21 an hour from 1 April 2027.
The announced rates for 18–20-year-olds and qualifying apprentices are £11.27 and £8.31 respectively. The £8.31 rate also applies to 16–17-year-olds.
What does this mean? At 37.5 paid hours a week for 52 weeks, the adult rate increase adds £975 to annual gross pay, £81.25 a month on average. Your take-home increase will depend on tax, deductions and any benefit changes.
Your money tip: Check your payslip when the new rate applies, then update your budget using your actual take-home pay.
2. Unchanged income tax rates do not guarantee an unchanged bill
The main income tax rates on earnings have not increased in this Budget. The standard Personal Allowance remains £12,570.
However, the threshold freeze through 5 April 2031 was previously announced. It is not a new change from this Budget. As earnings rise against frozen thresholds, more of your income can become taxable. Scottish income tax bands and rates on earnings differ.
What does this mean? A pay rise can still increase your tax bill even when headline tax rates stay the same. What matters for your budget is the extra income you actually receive after deductions.
Your money tip: If your pay changes, check your expected take-home income rather than assuming the entire increase is available to spend.
3. Cash ISA savers keep the current limit
The government has scrapped the planned reduction in the cash ISA limit.
What does this mean? You can continue to put up to £20,000 into cash ISAs within your overall £20,000 annual ISA allowance.
Your money tip: Compare interest rates, access restrictions and the tax you would pay outside an ISA. Choose an account that fits around your financial goals and timeframes.
4. Tax on savings interest and rental income is set to rise
From 6 April 2027, the planned basic, higher and additional rates on savings income are 24%, 44% and 49%.
These include a further two-percentage-point rise announced this year on top of the increase announced in 2025. Compared with today’s 20%, 40% and 45%, the total difference is four percentage points.
The Personal Savings Allowance remains £1,000 for basic-rate taxpayers and £500 for higher-rate taxpayers; additional-rate taxpayers have no Personal Savings Allowance. Other reliefs may apply.
What does this mean? A basic-rate taxpayer receiving £1,500 of annual interest, with a full £1,000 allowance and no other reliefs, would pay £120 on the remaining £500 at 24%, compared with £100 at today’s 20% rate.
The planned property-income rates are also 24%, 44% and 49%. Savings rates apply UK-wide; the published property rates cover England, Wales and Northern Ireland, with devolved powers to bear in mind.
Your money tip: Estimate the interest across your taxable savings accounts. If you’re a landlord, review your rental income, allowable expenses and available tax reliefs to check how much you may need to set aside. If you’re unsure, use HMRC’s guidance or seek help from a qualified tax professional.
5. Some households will receive energy support
A £100 Household Energy Payment is planned from January 2027 for eligible households living in their main home in council tax bands A–D in England. Full eligibility rules are still to be published. The devolved governments will decide how to use their additional funding.
The proposed removal of gas standing charges does not mean those costs disappear. They would move into unit prices, so the effect depends on how much gas you use. Implementation is being targeted for the end of 2027 or as soon as possible afterwards.
What does this mean? The payment could provide a one-off contribution towards eligible households’ bills. A change to standing charges would affect households differently, so compare the full annual cost rather than one part of a tariff.
Your money tip: Check your council’s official payment guidance. When comparing energy tariffs, use your own consumption, including unit prices and standing charges and the full estimated annual cost.
6. Your side hustle allowance is set to increase
The government plans to raise the trading allowance, often called the side hustle allowance, from £1,000 to £3,000, effective from 6 April 2027, through Finance Bill 2026-27.
This concerns qualifying trading and miscellaneous income before expenses. It is not an allowance against employment pay, and exclusions apply.
What does this mean? Someone with £3,000 of eligible receipts, no expenses and a 20% tax rate could save £400 compared with the current £1,000 allowance, assuming their Personal Allowance is already used, and no other relief applies.
Your money tip: Keep a record of income and expenses. When comparing claiming actual expenses with using the allowance, you cannot deduct both against the same income.
7. A targeted tax reduction for pensioners is planned
From 6 April 2027, the proposed Pension Tax Allowance will reduce income tax for eligible people at or above State Pension age with low total incomes.
It is based on total income, not just the State Pension. The full reduction applies up to the value of the full new State Pension and then tapers. It does not make every pensioner’s income tax-free.
What does this mean? You may qualify for a reduction even if some of your income comes from work or a private pension. Your total income determines eligibility and how much support applies.
Your money tip: Add together your income from pensions, work, savings and other sources before checking eligibility.
8. Family support changes to come later
Eligible self-employed fathers, partners and adopters in Great Britain are due to gain access to parental pay from April 2029.
Reform of the Carer’s Allowance earnings cliff edge is planned during 2030–31 in England and Wales, replacing the sudden loss of the benefit with a taper. The existing earnings rules still matter until then.
What does this mean? These measures could improve support in future, but they will not change what you can claim today. Families and carers should continue to use the current rules when planning their finances.
Your money tip: Plan around today’s entitlements and reporting rules. Revisit future support when eligibility and application guidance become available.
9. New funding and support for female founders
The Budget announced a new scale-up programme for female founders. The British Business Bank also confirmed a further £100 million commitment next financial year to support women-led businesses and funds.
This is not a guaranteed grant for every woman running a business. Access, funding routes and eligibility will depend on the programmes involved.
What does this mean? There may be future opportunities to access funding or business support, but the announcement does not establish that your business qualifies. Wait for the relevant programme’s criteria and application route.
Your money tip: Prepare a clear cash-flow forecast and funding purpose, then check official programme requirements before applying.
Your practical next steps
- Clarity: Choose the two or three announcements that affect you most. Note when they start and what information you need to check.
- Confidence: You don’t have to overhaul your finances overnight. Start with a clear picture of what comes in, what goes out and what may change.
- Connect: Link your next action to what matters most to you – whether that’s financial security, family goals or a future home. Set a date to review your progress.
Want to understand what these changes mean for you and your goals? Book a discovery call to explore how we can help.
This article provides general financial education, not regulated advice or a personal recommendation. Tax treatment and eligibility depend on individual circumstances. Information checked on 29 October 2026; announced measures may be amended and may require legislation.
Leave A Comment